Overview of IRS Tax Levy Issues

Overview of IRS Tax Levy Issues
An IRS tax levy is a seizure of your property to pay a income tax debt owed. A tax levy is different than a income tax lien. A tax lien is similar to a mortgage on your property, and is used to make a claim against the property as a security interest. An IRS tax levy is used to actually take the property once a tax lien is placed on the property.
If you have outstanding tax bills, the IRS (or NYS Tax dept.) may try to seize your property (bank accounts, real property), etc. and sell that property to pay off the tax debt.
Types of property the IRS or NYS would try to Levy:
- Car, boat, or house (in some cases), or
- Wages, retirement accounts, dividends, bank accounts, rental income, accounts receivable from a business, the cash loan value of your life insurance, or commissions.
The IRS usually levies only after these three requirements are satisfied:
- A tax was assessed;
- The tax assessed remains unpaid; and
- A final notice of levy is mailed to the taxpayer. The notice is titled: Final Notice of Intent to Levy and Notice of Your Right to A Hearing (levy notice) at least 30 days before the levy.
If there is an IRS tax levy on your wages or bank account, this would likely cause a hardship to you and it can be appealed. If it is determined the income tax levy is creating an immediate economic hardship, the IRS may release the levy. For wage levies, Employers generally have one full pay period cycle after receiving the Notice of Levy on Wages, Salary and Other Income before they are required to send in any funds to the IRS, thus allowing some to time to correct the problem by a payment plan. If you need assistance with an IRS Tax Levy, please contact us.
Get relief now
Your tax problem has a solution. Contact Tim Hart today for immediate guidance.
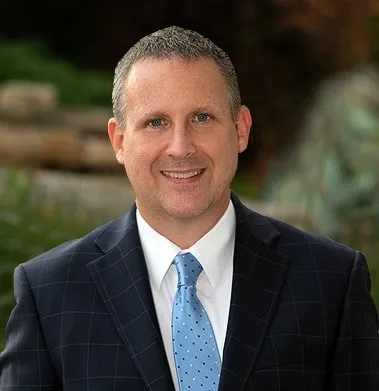
Attorney Timothy Hart
Timothy S Hart, the founding partner of the tax law firm of Timothy S. Hart Law Group, P.C. is both a New York Tax Lawyer & Certified Public Accountant. His area of expertise includes innovative solutions to solve your Internal Revenue Service and New York State tax problems, including tax settlements through the Federal and New York State offer in compromise programs, filing unfiled tax returns, voluntary disclosures, tax audits, and criminal investigations.