Mileage Logs: Keeping records is not enough to guarantee tax deductions

Mileage Logs: Keeping records is not enough to guarantee tax deductions
Every year the Internal Revenue Service issues optional standard mileage rates used to calculate the deductible costs of operating an automobile for business, charitable, medical, or moving purposes. Starting on January 1, 2013, the stand mileage rates for the use of an automobile are:
- 56.5 cents per mile for business miles driven
- 24 cents per mile driven for medical or moving purposes
- 14 cents per mile driven in service of a charitable organization
Taxpayers also have the option of calculating the actual costs of using their vehicle rather than using the standard mileage rates.
To substantiate your deductions for tax audits, you must keep good records. But sometimes a mileage log is not enough to guarantee that you will substantiate the deduction. The records that you keep must be precise and thorough. Keeping extensive records is beneficial because if you are audited, you have the documentation to back up your claims.
A 2003 Tax Court case reinforced the idea that just having a mileage log is not necessarily good enough to sustain deductions under an income tax audit. In the case, Willie Moore was employed by the City of Houston, and owned three Schedule C businesses with his wife. The couple owned three automobiles, two of which were used for business purposes. As shown at the income tax audit, the Moores kept mileage logs for their two business automobiles, consisting of twelve pages, one for each month, with each page having an entry or multiple entries for each day of the month. Mr. Moore used his own shorthand for the locations that he traveled to, and used generalized terms in the stated business purpose for the trip. The Moores used the standard deduction instead of actual expenses to deduct their automotive expenses, and the total for these expenses was over $30,000. Under the tax audit, the IRS claimed that the mileage logs did not meet the requirements of the tax law. The Tax Court ruled that the mileage log had too many errors and questionable entries, and therefore were unreliable, and the tax audit results were correct. Due to this, all of the automotive expenses were disallowed.
The tax code is a complex document, and sometimes the assistance of a lawyer can help, because when you file your return, you should be able to receive the proper amount in tax deductions after an income tax audit.
Get relief now
Your tax problem has a solution. Contact Tim Hart today for immediate guidance.
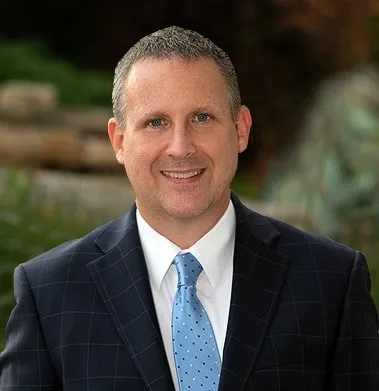
Attorney Timothy Hart
Timothy S Hart, the founding partner of the tax law firm of Timothy S. Hart Law Group, P.C. is both a New York Tax Lawyer & Certified Public Accountant. His area of expertise includes innovative solutions to solve your Internal Revenue Service and New York State tax problems, including tax settlements through the Federal and New York State offer in compromise programs, filing unfiled tax returns, voluntary disclosures, tax audits, and criminal investigations.